Financial Compatibility Before Marriage: The Transparent Money Talk Most Couples Avoid
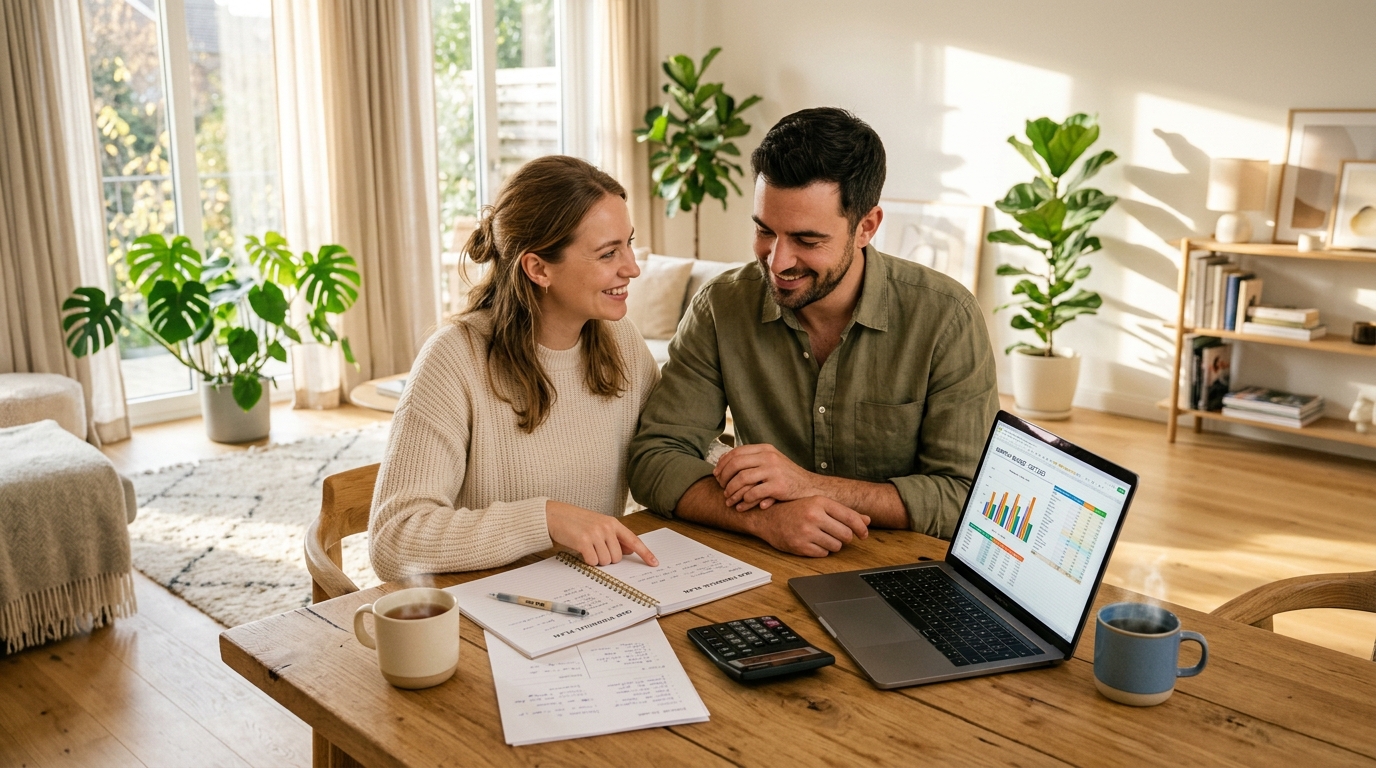
Money is the leading cited cause of marital distress worldwide. Yet couples enter lifelong partnerships with zero knowledge of their partner's credit scores, debt obligations, or financial psychology. Here is your comprehensive pre-marital financial survival guide.
Disclaimer: This guide provides relational and behavioral finance perspectives. For legal prenuptial or formal wealth structures, consult certified professionals.
Listen to this Masterclass on the go
You can disagree about music, favorite holiday destinations, or interior paint colors and still enjoy a wonderful marriage. But if you fundamentally disagree on how money is earned, spent, saved, invested, and shared with extended family, your relationship will exist in a permanent state of simmering resentment.
In traditional Indian households, talking about money before marriage is labeled 'greedy', 'selfish', or 'inauspicious'. We are conditioned to treat financial discussions as taboo, while simultaneously spending life savings on gold jewelry and lavish banquets. The result? Within 90 days of the wedding, spouses discover undisclosed credit card debts, secret parental remittances, and fundamentally incompatible spending habits.
Calculate your long-term compounding net worth and lifestyle milestones with our free Rich By 40 Calculator and Smart Loan EMI Calculator.
Explore Wealth & Loan CalculatorsThe 4-Stage Operating System: Financial Compatibility Before Marriage: The Transparent Money Talk Most Couples Avoid
Tap each stage below to explore the chronological step-by-step framework:
Look at consistent effort rather than late-night sweet texts.
1. The 5 Pre-Marital Financial Red Flags
The Financial Danger Audit
Warning signs that indicate deep economic dysfunction before marriage
Chronic Secrecy & Defensive Avoidance
If asking to see salary slips, investment balances, or credit reports produces anger, guilt-tripping, or accusations of distrust, they are hiding significant liabilities.
Addictive High-Risk Speculation
A pattern of gambling on volatile crypto schemes, daily F&O options trading, or borrowing money to fund speculative get-rich-quick bets.
Entitled Lifestyle Inflation
Spending 100% of income on luxury designer clothing, VIP clubbing, and expensive cars while having zero emergency fund savings. Read The Psychology of Money & Abundance for mindset shifts.
Unilateral Financial Support to Extended Family
Sending large percentages of monthly income to parents or siblings without mutual disclosure or consultation with their spouse.
Financial Control and Weaponization
Insisting that one partner must surrender their entire paycheck, or that all assets must remain exclusively under one person's control.
2. The 3-Account Financial Blueprint for Married Couples
How should modern working couples organize their banking? The most resilient and friction-free architecture implemented by financially mature couples is **The Hybrid Proportional Model**:
Why 90% Struggle vs How the Top 10% Win
- ✕Chasing daily hype, impulsive shortcuts, and emotional overreaction.
- ✕Operating without clear boundaries or written mathematical rules.
- ✕Giving up after 2 weeks when instant dopamine gratification fades.
- ✓Automated daily discipline that compounds quietly in the background.
- ✓Unshakable emotional calm during temporary setbacks or market dips.
- ✓Staying in the game for decades to unlock exponential compounding wealth.
| Account Type | Ownership | Funding Source | Permitted Expenses |
|---|---|---|---|
| Joint Household Account | Both Partners (Co-signers) | Proportional contribution (e.g. 60/40 based on income) | Rent, home EMIs, utilities, groceries, maid salaries, joint insurance |
| Joint Wealth & Goals Account | Both Partners (Co-signers) | Proportional monthly SIP transfers | Long-term index funds, emergency fund, annual vacation savings, down payments |
| Partner A Independence Account | Partner A Sole Name | Remaining personal income balance | Personal hobbies, personal gifts, clothes, guilt-free discretionary spending |
| Partner B Independence Account | Partner B Sole Name | Remaining personal income balance | Personal hobbies, personal gifts, clothes, guilt-free discretionary spending |
Why does this model work so brilliantly? Because it creates **shared solidarity without eliminating personal freedom**. You never have to ask your spouse for 'permission' to buy a pair of shoes or take your friends out for coffee, because you are using your personal independence account. Yet the household bills, retirement corpus, and emergency buffers are rigorously protected.
3. The 4 Essential Discussions Before Walking Down the Aisle
Smart Doubt Clearing AssistantLIVE AI
इस आर्टिकल को पढ़ते समय कोई भी सवाल या शंका हो, सीधे यहाँ पूछें:
Before exchanging vows, sit down with a laptop and a cup of tea. Review your mutual goals alongside Paisa Ya Pyaar? Can Love Survive Without Money? and Financial Stability vs Emotional Connection. Establish crystal clarity on these four pillars:
"Money is the leading cited cause of marital distress worldwide. Yet couples enter lifelong partnerships with z..."
— Bhaway Bhalla • System Principle
- Complete disclosure of all outstanding liabilities (personal loans, auto loans, credit card balances, educational debt).
- A formal commitment to maintain a 6-month liquid emergency fund in safe liquid funds before upgrading cars or homes.
- Clear boundaries on parental financial support: How much monthly assistance will be given to parents, and under what circumstances?
- An annual financial review cadence: Sitting down together every December to review investment compounding, career raises, and next year's budget.
Where Should You Focus Your Energy First?
Click any quadrant to reveal high-leverage execution priorities:
Automate your basic routines today (auto-SIP, room rent sub-limit audit, muting toxic notifications).
Skill-stacking AI automation, restructuring portfolio, setting deep-work boundaries with family/partner.
Checking monthly statements, standard car checkup, weekly housekeeping habits.
Overthinking past decisions, arguing on social media comments, timing daily stock market fluctuations.
Bhaway is a systems builder, AI architect, and digital media founder. Having managed enterprise technical operations across Concentrix (Dell & Uber) and launched platforms like AI Is Everywhere and PromptLagao, he documents first-principles frameworks across human relationships, compounding wealth, and AI leverage.
Stay Connected Inside Bhaway's Digital Headquarters
Every system, brand, and framework discussed in this article is actively maintained and operated in public. Continue your exploration:
Ask BB • Article Explainer & Summary
Interactive AI breakdown for "Financial Compatibility Before Marriage: The ..."
Money is the leading cited cause of marital distress worldwide. Yet couples enter lifelong partnerships with zero knowledge of their partner's credit scores, debt obligations, or financial psychology. Here is your comprehensive pre-marital financial survival guide.
- •Financial Compatibility Is Behavioral, Not Just Income-Based: Two high earners who are compulsive spenders will face catastrophic financial warfare; two modest earners with mutual discipline will build generational wealth.
- •The 'Secret Debt' Trap: Concealing personal loans, EMIs, or business liabilities before marriage is a profound violation of trust that poisons marital intimacy immediately upon discovery.
- •The 3-Account Operating Model: Smart modern couples utilize a Joint Living Account (for rent, groceries, EMIs, utilities) funded proportionally, alongside Private Independence Accounts for personal autonomy.
What Should I Read Next?
You just finished exploring "Financial Compatibility Before Marriage: The Transparent Money Talk Most Couples Avoid". To maximize your retention and avoid fragmented reading, follow this structured 3-step sequence:
Get 1 Practical Idea Daily.
No spam, no promotional fluff. A 2-minute actionable blueprint on modern relationships, quiet wealth compounding, or AI execution delivered directly to your inbox every morning.
FAQ
Frequently Asked Questions
Should couples split household expenses 50/50 if one earns significantly more?
No. Strict 50/50 splits when one partner earns ₹25 Lakhs and the other earns ₹7 Lakhs creates severe financial exhaustion and resentment for the lower earner. Proportional splitting (e.g. 75/25 based on income ratios) is far healthier and equitable.
Is a prenuptial agreement valid in India?
Under the Hindu Marriage Act and Special Marriage Act, prenuptial agreements are generally not legally binding in Indian courts because marriage is considered a sacred union rather than a commercial contract. However, pre-marital financial disclosures and Memorandums of Understanding (MOUs) carry evidentiary weight in mutual asset distribution settlements.
How do we handle it if one partner is a natural saver and the other is a spender?
Establish the 3-Account model. As long as the joint household and joint investment allocations are automatically deducted on the 1st of every month, the spender has complete freedom to enjoy their remaining personal allowance without being micromanaged.
Topic Tags
Recommended Interactive Tools For You
Put the concepts in this article into immediate practice. Zero paywalls, instant calculations, and confidential browser-local analysis.
Smart SIP & Compounding Calculator
Visualize how boring monthly investing creates life-changing compounding wealth, adjusted for 6% Indian inflation.
Pre-Marriage 25-Point Checklist
Interactive audit covering the 25 uncomfortable conversations every couple must resolve before marriage.
MindMatch™ Marriage & Kundli
Fuses traditional Kundli matching with financial transparency, communication styles, and family boundaries.
Indian Life Milestone & Cost Calculator
Project inflation-adjusted costs for major Indian milestones and compute required monthly investment targets.
Community Discussion
Comments (1)
Super insightful post! The clear breakdown made it effortless to understand and apply.
Thanks Aman! Really glad this clicked for you. Let me know what you think once you try it out!